Factor Lab Daily Brief 2026-09-04
US close Thu (09-03) incorporated: momentum-reversal persists for an 8th consecutive day with new lows on both fronts — momentum IC -0.221, ICIR -1.92, t-stat -11.84, only 2.6% positive cross-sections, long-short spread +6.75% monotonic; IT sector momentum IC deepened to -0.506 (long-short +20.38%), Financials (IC -0.298) and Industrials (IC -0.248) keep weakening, Real Estate remains the only significant positive-momentum sector (IC +0.209); volatility factor IC +0.030 still insignificant (p=0.325), value factors stay broken. Anomaly detection: same momentum sign-flip alarms as yesterday persist — IT/Financials beyond 3σ, Industrials/Consumer Discretionary/Staples beyond 2σ positive-to-negative, Real Estate +2σ high, Utilities p-value lost significance (0.416). No new alert types.
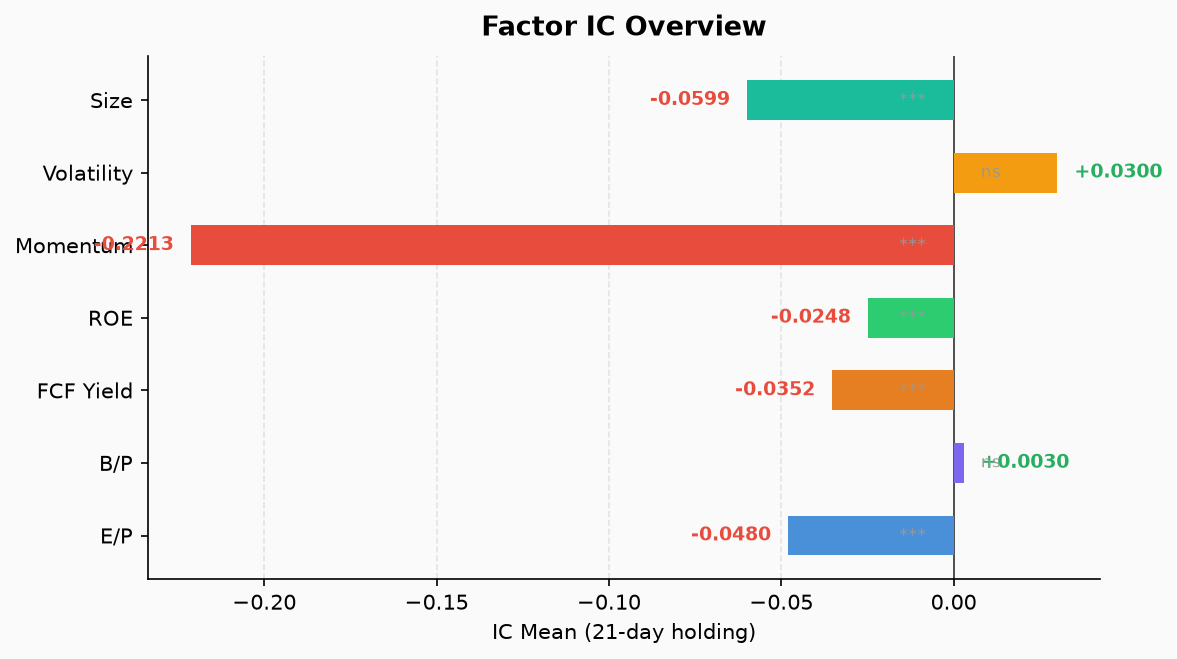
Full-Factor IC Test (21-day holding)
| Factor | IC Mean | ICIR | t-stat | p-value | % Positive IC | L/S Return%(Q1-Q5) |
|---|---|---|---|---|---|---|
| EP | -0.048 | -0.52 | -3.99 | 0.000 | 28.3% | +2.98% |
| BP | +0.003 | +0.05 | +0.35 | 0.728 | 48.3% | +1.13% |
| FCF Yield | -0.035 | -0.54 | -4.14 | 0.000 | 25.0% | +2.48% |
| ROE | -0.025 | -0.68 | -5.26 | 0.000 | 26.7% | +0.76% |
| Mom | -0.221 | -1.92 | -11.84 | 0.000 | 2.6% | +6.75% |
| Vol | +0.030 | +0.16 | +1.00 | 0.325 | 59.0% | -1.07% |
| Size | -0.060 | -0.80 | -4.91 | 0.000 | 23.1% | +3.82% |
Key observations:
- Momentum reversal persists for an 8th consecutive day and hits new lows (key): Momentum IC -0.2213 (yesterday -0.2152, lower for the 14th consecutive historical record), ICIR -1.92, t-stat -11.84, only 2.6% of 39 cross-sections positive. Low-momentum quintile (Q1) averaged +6.75%, high-momentum (Q5) -0.00%, long-short spread +6.75% monotonic. Reversal regime intact after incorporating the Thu (09-03) US close.
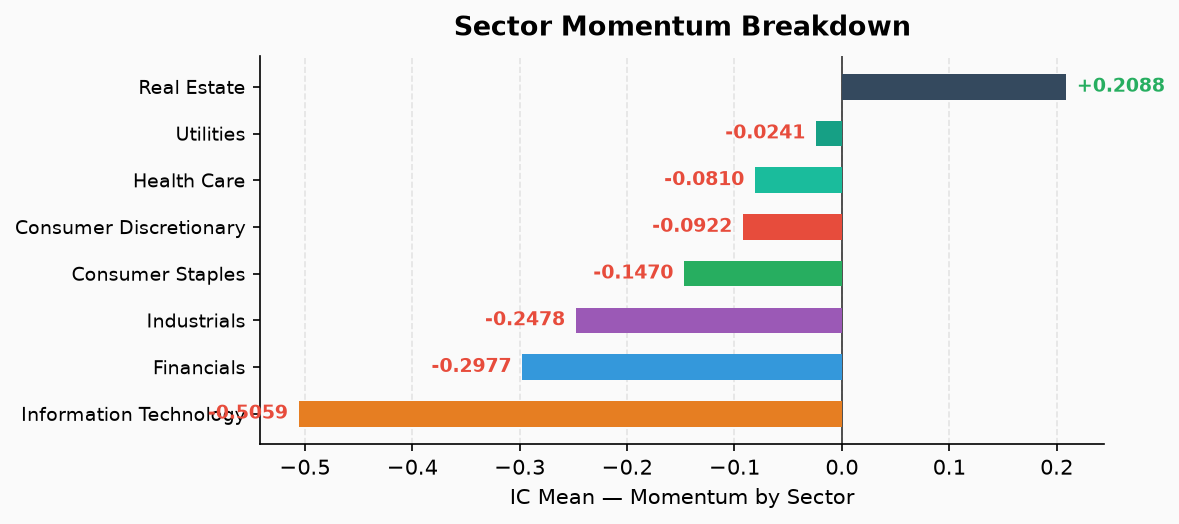
- IT sector momentum hits a new low (key): Sector IC -0.506, down from -0.484 yesterday; long-short spread +20.38% is a new cycle high — the correction in previously strong tech names is still accelerating with no stabilization in sight.
- Financials and Industrials keep weakening: Financials IC -0.298, only 2.6% positive cross-sections, long-short +5.62% monotonic; Industrials IC -0.248, spread +8.70%.
- Real Estate remains the only significant positive-momentum sector: IC +0.209, ICIR +0.67, 72.0% positive, p=0.003 — defensive/safe-haven tilt persists.
- Value factors stay broken: EP (ICIR -0.52), FCF Yield (ICIR -0.54), ROE (ICIR -0.68) all keep significant negative IC.
- Volatility factor still insignificant: Vol IC +0.030 (yesterday +0.026), p=0.325 — low-vol outperformance signal still missing.
- Data note: This update incorporates the US Thu (09-03) close — genuinely new data.
Sector Momentum Breakdown
| Sector | Stocks | IC Mean | ICIR | % Positive IC | L/S Return%(Q1-Q5) |
|---|---|---|---|---|---|
| Information Technology | 73 | -0.506 | -2.09 | 7.7% | +20.38% |
| Financials | 76 | -0.298 | -1.85 | 2.6% | +5.62% |
| Industrials | 79 | -0.248 | -1.71 | 7.7% | +8.70% |
| Consumer Staples | 36 | -0.147 | -0.96 | 17.9% | +6.04% |
| Consumer Discretionary | 48 | -0.092 | -0.58 | 33.3% | +2.70% |
| Health Care | 59 | -0.081 | -0.36 | 41.0% | +1.44% |
| Utilities | 31 | -0.024 | -0.13 | 43.6% | +0.11% |
| Real Estate | 31 | +0.209 | +0.67 | 72.0% | -3.86% |
Sector highlights:
- IT momentum is the most negative sector-wide and hits a new low (key): Sector IC -0.506, down from -0.484 yesterday; long-short spread +20.38% is a new cycle high — the main driver of the market-wide reversal, with tech leaders still catching down.
- Financials and Industrials keep weakening: Financials IC -0.298, only 2.6% positive cross-sections, long-short +5.62% monotonic; Industrials IC -0.248, spread +8.70%.
- Real Estate keeps the only significant positive momentum: IC +0.209, ICIR +0.67, 72.0% positive, p=0.003 — defensive tilt intact.
- Utilities momentum keeps failing: Utilities IC -0.024 (p 0.416) insignificant, further weakening from near zero yesterday.
Anomaly Detection (🔴/⚠️)
Today’s alerts mirror yesterday — all are continuation signals of the momentum-reversal regime (day 8), no new alert types:
| Sector | Latest IC | Historical Mean | z-score | Alert |
|---|---|---|---|---|
| Information Technology | -0.506 | +0.415±0.293 | -3.15 | 🔴 sign-flip + ⚠️ >3σ low |
| Financials | -0.298 | +0.244±0.176 | -3.09 | 🔴 sign-flip + ⚠️ >3σ low |
| Industrials | -0.248 | +0.207±0.157 | -2.90 | 🔴 sign-flip + ⚠️ >2σ low |
| Consumer Discretionary | -0.092 | +0.209±0.116 | -2.61 | 🔴 sign-flip + ⚠️ >2σ low |
| Consumer Staples | -0.147 | +0.162±0.126 | -2.45 | 🔴 sign-flip + ⚠️ >2σ low |
| Utilities | -0.024 | +0.171±0.077 | -2.53 | ⚠️ >2σ low + p 0.035→0.416 lost significance |
| Real Estate | +0.209 | +0.135±0.030 | +2.47 | ⚠️ >2σ high |
Note: the alert baseline’s historical mean covers the May–June positive-momentum era (+0.1 to +0.4); momentum turned negative in late August and has persisted for two weeks, so these “positive-to-negative” alerts are persistence markers of an existing regime, not new discontinuities today.
Summary
After incorporating the US Thu (09-03) close, momentum reversal persists for an 8th consecutive day with new lows in both market-wide IC and IT sector IC: momentum IC -0.221, IT sector IC -0.506 (long-short +20.38%), Financials and Industrials keep weakening, Real Estate remains the only significant positive-momentum sector. The volatility factor is still insignificant and value factors stay broken.
Risk signals to watch:
- Momentum reversal keeps deepening to new lows: ICIR -1.92, t=-11.84, IT sector IC -0.506 at a fresh low; 5 sectors keep momentum sign-flip alarms beyond 2-3σ — the correction in previously strong tech names has not stopped
- Reversal is statistically extreme: several consecutive days of reversal, long-short spread +6.75% monotonic — more likely a genuine regime than a data artifact; chasing recently strong stocks near-term carries high risk
- Real Estate (IC +0.209) remains the only significant positive-momentum sector: defensive style persists; watch rates and REIT fund flows
- Volatility factor still insignificant (p=0.325): low-vol outperformance signal missing; breadth confirmation of any style shift still absent
Strategy takeaway: the momentum-reversal regime is unchanged with Tech deepening; chasing recently strong stocks remains risky. Value factors stay broken, and defensive (Real Estate) is relatively preferred. Maintain low-momentum exposure and wait for a stabilization signal before rotating back.