Factor Lab Daily Report 2026-08-22
Momentum reversal deepens for a third consecutive trading day: momentum IC falls further from -0.169 to -0.180, ICIR -1.37, IC positive ratio only 7.7%, long-short spread widens to +5.77%; IT sector momentum IC drops from -0.304 to -0.328 with a long-short spread of +13.08%, a fresh stage high, while Financials (IC -0.205) and Industrials (IC -0.206) weaken in tandem; the volatility factor turns non-significant (p=0.067), and only Real Estate keeps positive momentum (IC +0.206). This report incorporates Friday (08-21) close data.
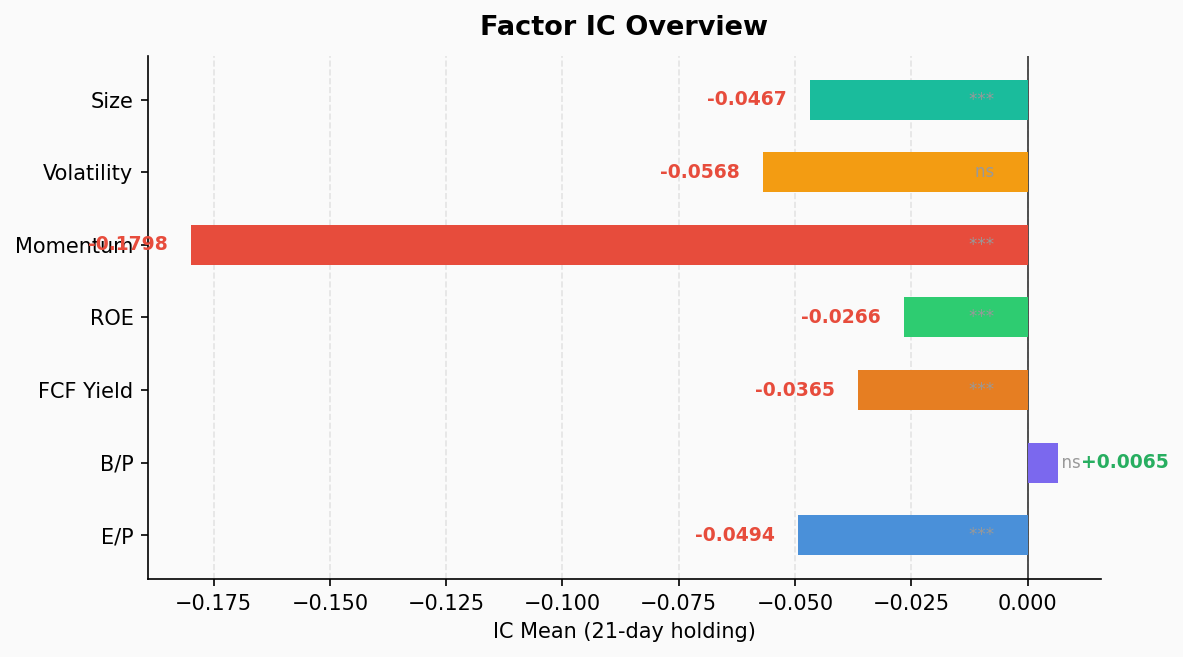
Full-Factor IC Test (21-day holding)
| Factor | IC Mean | ICIR | t-stat | p-value | IC Positive % | L/S Ret % (Q1-Q5) |
|---|---|---|---|---|---|---|
| EP | -0.049 | -0.56 | -4.27 | 0.000 | 28.3% | +3.00% |
| BP | +0.006 | +0.10 | +0.77 | 0.446 | 50.0% | -0.15% |
| FCF Yield | -0.036 | -0.57 | -4.35 | 0.000 | 23.3% | +2.53% |
| ROE | -0.027 | -0.70 | -5.41 | 0.000 | 28.3% | +1.34% |
| Mom | -0.180 | -1.37 | -8.46 | 0.000 | 7.7% | +5.77% |
| Vol | -0.057 | -0.31 | -1.89 | 0.067 | 38.5% | +1.80% |
| Size | -0.047 | -0.59 | -3.64 | 0.001 | 25.6% | +2.78% |
Key Observations:
- Momentum reversal deepens for the third consecutive day (key point): Momentum IC slips further from -0.169 (prior report) to -0.180, ICIR worsens from -1.34 to -1.37, and the IC positive ratio stays at only 7.7% (just 3 of 39 cross-sections positive), with the t-statistic becoming even more extreme at -8.46. Low-momentum stocks (Q1) average +5.43% while high-momentum (Q5) sit at -0.33%; the long-short spread widens to +5.77%. “Winners keep winning” has now failed to hold for three straight windows, and the catch-up decline in previously strong names shows no sign of stopping.
- Value factors remain ineffective: EP (ICIR -0.56), FCF Yield (ICIR -0.57) and ROE (ICIR -0.70) all maintain significantly negative IC. Low-valuation/high-ROE stocks keep underperforming; “cheap” still does not pay.
- BP still useless: ICIR only 0.10, p=0.45; book value provides no discriminating power.
- Volatility factor turns marginal: Vol IC -0.057, p-value rising from 0.033 to 0.067, no longer statistically significant; low-volatility outperformance persists but with fading strength.
- Size factor stays negative: Size IC -0.047, ICIR -0.59; small-cap relative outperformance continues.
- Data note: This run incorporates Friday (08-21) close data (recalculated after the morning cache sync), adding one more trading day versus the prior report. The third consecutive day of deepening momentum reversal confirms direction rather than being a data artifact.
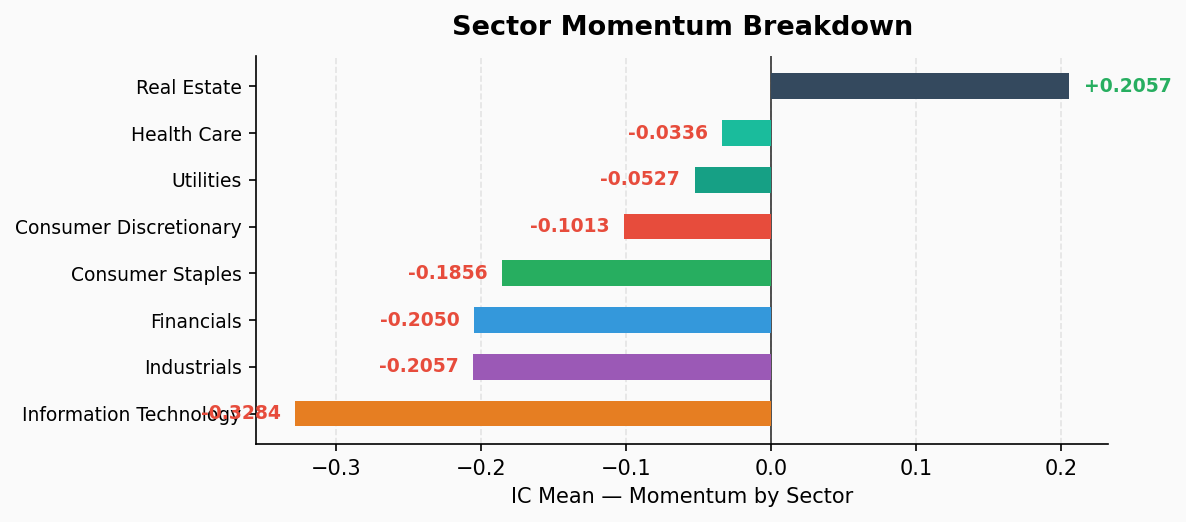
Sector Momentum Breakdown
| Sector | Stocks | IC Mean | ICIR | IC Positive % | L/S Ret % (Q1-Q5) |
|---|---|---|---|---|---|
| Information Technology | 73 | -0.328 | -0.87 | 23.1% | +13.08% |
| Industrials | 79 | -0.206 | -1.27 | 12.8% | +6.99% |
| Financials | 76 | -0.205 | -0.90 | 12.8% | +4.27% |
| Consumer Staples | 36 | -0.186 | -1.03 | 15.4% | +5.55% |
| Consumer Discretionary | 48 | -0.101 | -0.64 | 30.8% | +2.24% |
| Utilities | 31 | -0.053 | -0.25 | 35.9% | +0.46% |
| Health Care | 59 | -0.034 | -0.13 | 48.7% | +1.63% |
| Real Estate | 31 | +0.206 | +0.73 | 77.1% | -4.87% |
Sector Highlights:
- IT momentum deteriorates further (key point): Sector momentum IC drops from -0.304 to -0.328, the most negative across all sectors. Q1 (low momentum) returns +6.90% while Q5 (high momentum) reaches -6.19%; the long-short spread of +13.08% sets another stage high. The catch-up decline inside tech is still accelerating and is currently the market’s most violent reversal source.
- Financials and Industrials deepen in tandem: Financials IC -0.205 (prior -0.182) with IC positive ratio falling to 12.8%; Industrials IC -0.206 (prior -0.199) with a +6.99% long-short spread. Momentum leaders in these two heavyweight sectors continue to retreat broadly.
- Real Estate remains the only positive-momentum sector: IC +0.206, ICIR +0.73, IC positive ratio 77.1%, keeping its status as the sole positive-momentum sector with clear defensive/safe-haven traits.
- Health Care and Utilities lose momentum power: Health Care IC -0.034 (p=0.43) and Utilities IC -0.053 (p=0.13) are both non-significant; momentum has lost discriminating power in these sectors.
Summary
After incorporating Friday (08-21) close, the established momentum reversal deepened for a third consecutive trading day: momentum IC fell from -0.169 to -0.180, IT sector IC from -0.304 to -0.328, and Financials and Industrials weakened in tandem, while volatility and size factors remain negative — the market keeps favoring defensive and mean-reversion styles. The most notable change this report is Financials turning more negative (IC positive ratio only 12.8%), broadening the catch-up decline among heavyweight-sector momentum leaders.
Risk signals to watch:
- Momentum (ICIR -1.37, t=-8.46) and IT sector (IC -0.328) sit in extreme territory; anomaly detection keeps flagging multiple sectors beyond 2σ with sign-flip alarms — the concentrated pullback in previously strong names has now run for three trading days
- The reversal has deepened three days in a row with extreme statistical significance — more likely real market behavior than a data artifact; chasing recent winners short-term carries high risk
- Real Estate (IC +0.206) remains the sole positive-momentum sector; defensive style may persist — watch rates and REIT fund flows
- The volatility factor turned from significant to non-significant (p=0.067); the edge of low-volatility outperformance is fading, which may hint the style shift is entering its late stage, though confirmation is still needed
Strategy takeaway: The momentum reversal has run for three trading days with expanding magnitude, so chasing recently strong names short-term is risky. Value factors remain ineffective, while defensive styles (low-volatility / Real Estate) are relatively favored. Maintain low momentum exposure and wait for the reversal to stabilize before re-entering; also monitor the fading significance of the volatility factor as a marginal signal.