Factor Lab Daily Brief 2026-07-27
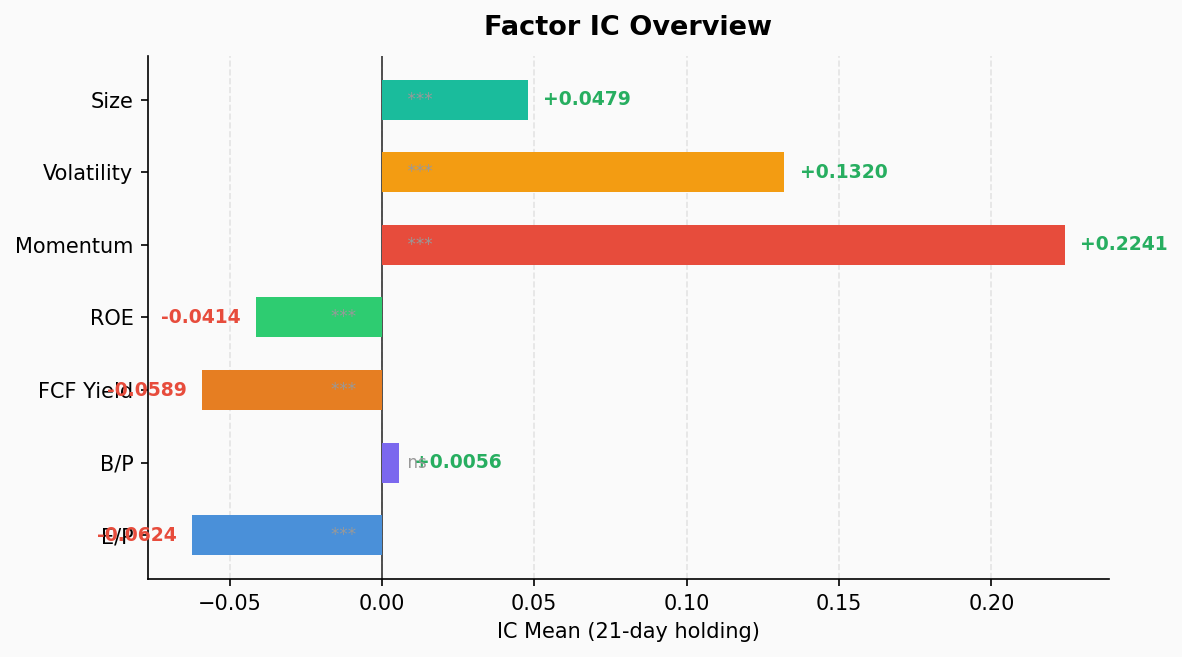
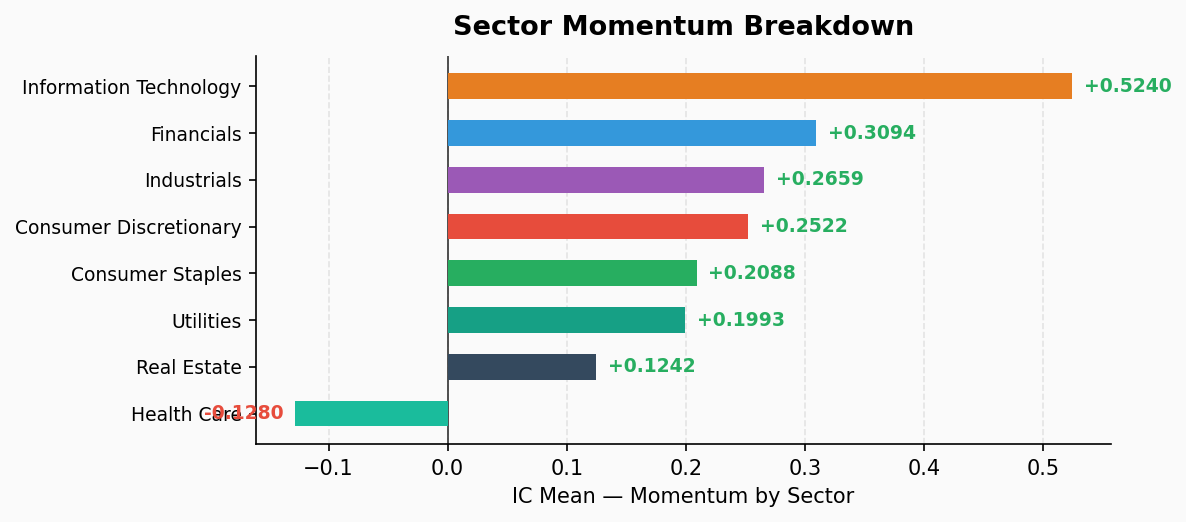
Momentum continues to dominate with ICIR 2.70, the strongest across all factors. Value factors remain uniformly negative — EP, FCF Yield, and ROE all show statistically significant negative IC. Information Technology leads sector momentum with IC mean 0.524 and Q5 21-day return of 27.2%. Health Care is the only sector exhibiting momentum reversal.
All-Factor IC Test
Data as of 2026-07-27. Sample covers S&P 500 constituents, 39 cross-sections (~8 months), 21-day holding period.
| Factor | IC Mean | ICIR | t-stat | p-value | IC Win Rate | Q1 Return | Q5 Return | Long-Short |
|---|---|---|---|---|---|---|---|---|
| Momentum | 0.224 | 2.70 | 16.62 | 0.000 | 100.0% | -0.12% | 7.95% | -8.07% |
| Volatility | 0.132 | 1.05 | 6.48 | 0.000 | 79.5% | 0.54% | 8.15% | -7.61% |
| Size | 0.048 | 1.25 | 7.70 | 0.000 | 87.2% | 2.45% | 4.51% | -2.06% |
| BP | 0.006 | 0.08 | 0.48 | 0.635 | 46.2% | 3.88% | 3.06% | 0.82% |
| ROE | -0.041 | -1.23 | -7.58 | 0.000 | 12.8% | 4.82% | 3.71% | 1.11% |
| FCF Yield | -0.059 | -1.43 | -8.79 | 0.000 | 7.7% | 5.64% | 2.60% | 3.04% |
| EP | -0.062 | -0.74 | -4.57 | 0.000 | 17.9% | 6.41% | 2.54% | 3.87% |
Key Findings
Momentum reigns supreme. IC mean of 0.224, ICIR 2.70, and a 100% positive IC rate — statistically extraordinary. The Q5 (high momentum) portfolio averaged 7.95% over 21 days, while Q1 (low momentum) returned -0.12%, yielding an 8.07 percentage point long-short spread.
Value factors are broken across the board. EP, FCF Yield, and ROE all exhibit negative and statistically significant IC. High EP stocks returned only 2.54% over 21 days compared to 6.41% for low EP stocks. This is not “value mean-reverting” — this is value systematically underperforming. The market is rewarding high valuations and growth expectations while punishing “cheapness.”
BP is the only neutral value factor. IC mean and ICIR both near zero, p-value 0.635 insignificant — book-to-price provides zero differentiation in the current market.
High volatility = high returns. Volatility factor IC is positive (0.132), long-short spread -7.61% — high-vol stocks significantly outperform low-vol. Classic risk-on behavior: capital is chasing beta.
Large-cap preference. Size factor IC 0.048, Q5 outperforms Q1 by ~2 percentage points. The market is concentrating into large caps; small and mid-caps are lagging.
Sector Momentum Decomposition
| Sector | IC Mean | ICIR | IC Win Rate | Q1 Return | Q5 Return | Long-Short |
|---|---|---|---|---|---|---|
| Information Technology | 0.524 | 2.58 | 100.0% | -1.35% | 27.19% | -28.54% |
| Financials | 0.309 | 2.63 | 100.0% | 0.61% | 7.80% | -7.19% |
| Industrials | 0.266 | 2.88 | 100.0% | -1.63% | 5.51% | -7.14% |
| Consumer Discretionary | 0.252 | 2.11 | 100.0% | -4.05% | 2.15% | -6.21% |
| Consumer Staples | 0.209 | 1.34 | 87.2% | -4.65% | 0.02% | -4.67% |
| Utilities | 0.199 | 1.01 | 76.9% | -2.29% | -1.66% | -0.63% |
| Real Estate | 0.124 | 0.84 | 74.4% | 1.12% | 4.95% | -3.83% |
| Health Care | -0.128 | -1.21 | 15.4% | 4.84% | -2.66% | 7.51% |
Information Technology is the momentum king. IC mean of 0.524, Q5 portfolio delivered 27.19% over 21 days versus -1.35% for Q1 — a near 29 percentage point long-short spread. Momentum stratification within IT is extreme: winners take all, losers get crushed.
Financials and Industrials are strong seconds. Both sectors show IC in the 0.26–0.31 range with ICIR above 2.6 — momentum is robust and persistent. Financials’ Q5 returned 7.80% while Q1 was still positive, indicating the entire sector is in an uptrend, with momentum stock selection amplifying gains further.
Health Care is reversing. IC of -0.128, ICIR -1.21 — the only sector with significantly negative momentum. Q1 (prior laggards) returned the highest at 4.84%, while Q5 (prior winners) returned -2.66%. Health Care is experiencing sharp mean reversion: what went up is coming down, what went down is bouncing.
Strategy Implications
The market is in a classic trend-following regime. Momentum’s dominance (ICIR 2.70, 100% win rate) indicates strong market directionality. Reversal strategies would have bled consistently during this period.
Do not bottom-fish value. EP, FCF Yield, and ROE are uniformly negative — this is not random noise. The market is systematically rewarding growth and momentum while punishing static cheapness. BP’s neutral reading confirms that even the last bastion of deep value has broken.
Sector rotation signal is clear: overweight Tech + Financials, underweight Health Care. Tech and Financials show the strongest momentum with consistent direction (negative long-short = profitable to go long winners / short losers). Health Care is in mean-reversion mode. If holding Health Care names, consider taking profits on recent outperformers.
Risk note: A 100% momentum win rate is unsustainable. When all factors point in the same direction, crowded-trade risk is accumulating. Maintain position-sizing discipline.