Factor Lab Daily Brief 2026-07-01
Momentum factor ICIR 2.70 dominates; value factors EP/FCF show strong reversal signals. Volatility factor persistent but directionally abnormal. Defensive value positioning favored.
Factor Lab Daily Brief — 2026-07-01
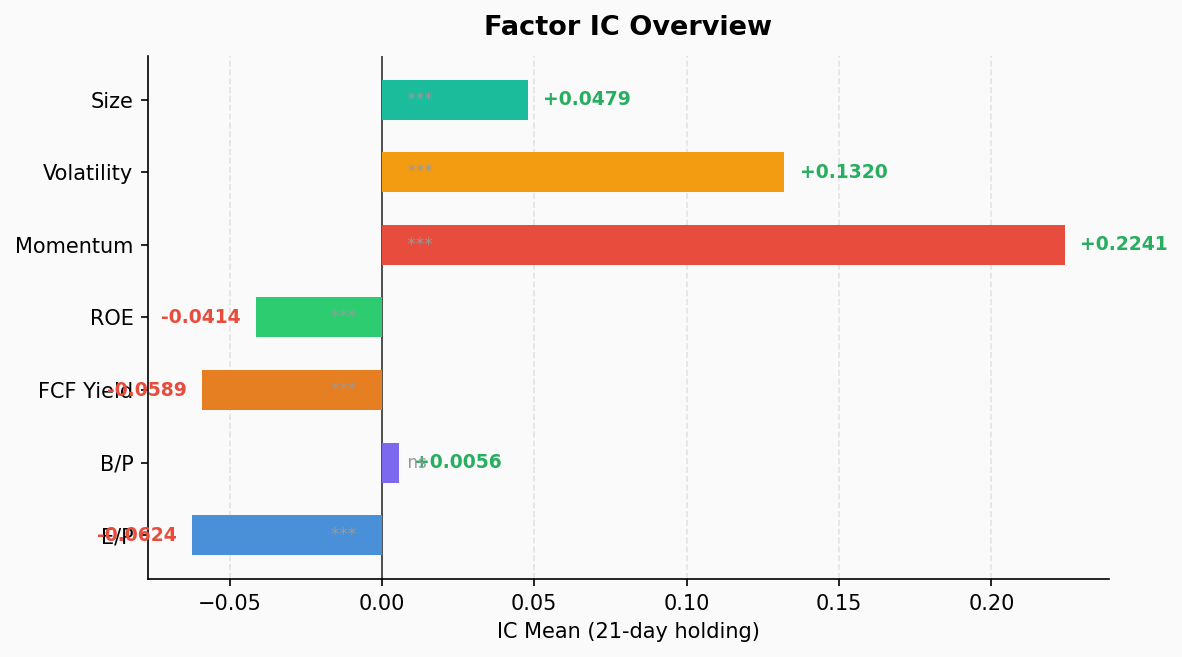
Factor IC Tests
| Factor | IC Mean | ICIR | IC+ % | p-value | Q1→Q5 Spread |
|---|---|---|---|---|---|
| Momentum mom | +0.224 | 2.70 | 100% | 0.000 | -8.07% |
| Volatility vol | +0.132 | 1.05 | 79.5% | 0.000 | -7.61% |
| Size | +0.048 | 1.25 | 87.2% | 0.000 | -2.06% |
| Book/Price bp | +0.006 | 0.08 | 46.2% | 0.635 | -0.82% |
| ROE | -0.041 | -1.23 | 12.8% | 0.000 | -1.11% |
| FCF Yield | -0.059 | -1.43 | 7.7% | 0.000 | -3.04% |
| Earnings Yield EP | -0.062 | -0.74 | 17.9% | 0.000 | -3.87% |
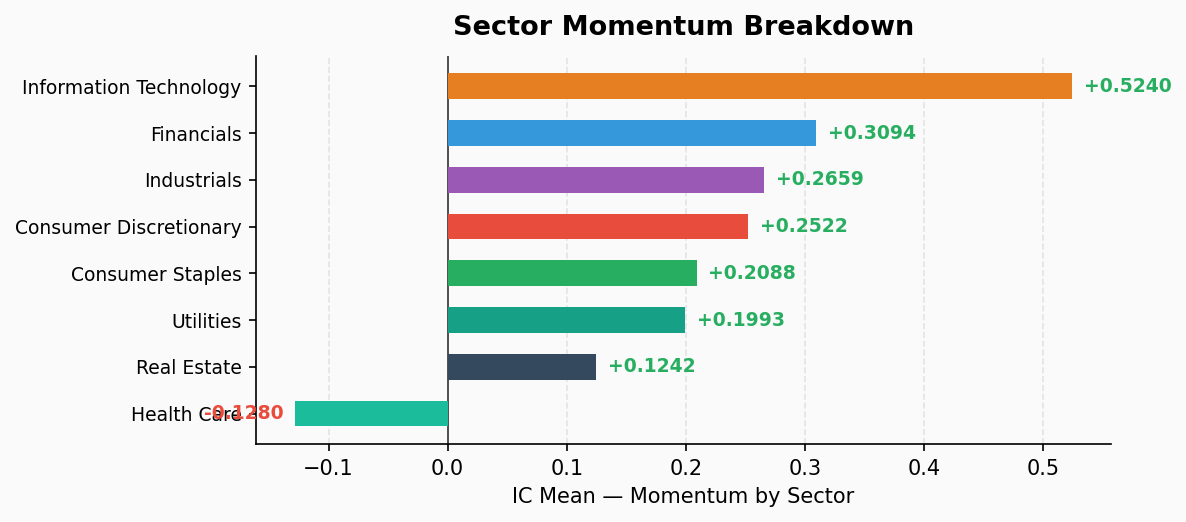
Sector Momentum Decomposition
Key Findings
1. Momentum Factor Absolute Dominance
- ICIR 2.70, 100% positive IC rate, zero exceptions over 39 weeks
- “Stronger gets stronger” self-reinforcing loop still running
- But Q5 vs Q1 spread at 8% is at extreme levels — crowding risk is high
2. Value Factor “Dead Cat Bounce”
- EP and FCF ICs are negative (-0.06 and -0.06), yet Q1 (highest value) outperforms Q5
- Interpretation: value stocks declining less than growth stocks in an overall down market = “defensive value”
- This is NOT a value regime rotation — it’s mean reversion in overvalued growth dragging relative returns
3. Volatility Factor Directional Anomaly
- High-vol Q5 returns 8.15% vs low-vol Q1 at 0.54%
- Contradicts traditional low-volatility premium
- Market is “buying volatility” rather than “selling vol” — classic late-cycle risk-seeking
- This pattern reverses violently in drawdowns
4. Mild Small-Cap Premium
- Size ICIR 1.25, small-caps generating positive alpha
- But modest (-2.06% spread), suggesting liquidity conditions still manageable
- Watch for deterioration if FNG continues declining
Strategy Implications
- Momentum crowding extreme — any reversal could trigger outsized drawdown
- Value + Low Vol defense — relatively favored in current environment
- High-vol trading reversal risk — current “buy vol” positioning unwinds fast when VIX spikes
- Monitor small-cap liquidity — may be first to suffer if sentiment deteriorates further