Factor Lab Daily Brief 2026-06-26
Momentum ICIR +2.70 dominates; value factors reverse; Healthcare shows mean reversion
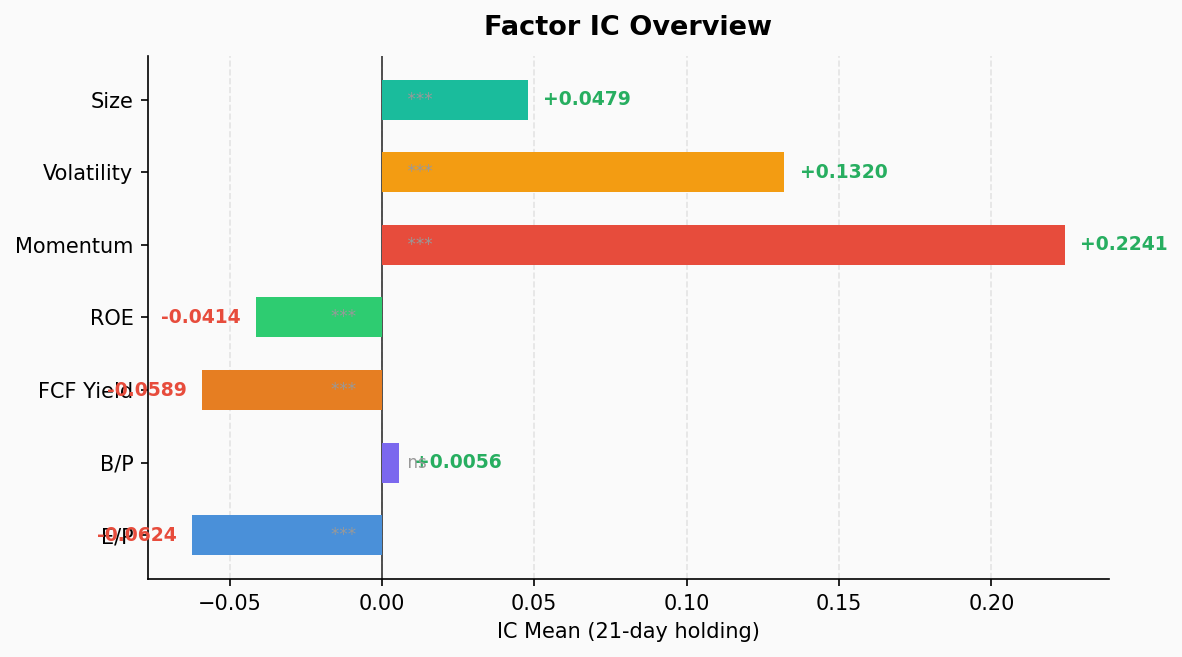
📊 Factor IC Tests (S&P 500, 21-day holding, 39 rolling periods)
| Factor | IC Mean | ICIR | p-value | Long-Short | Verdict |
|---|---|---|---|---|---|
| Momentum (mom) | +0.224 | +2.70 | 0.000 | -8.07% | 🟢 Strong positive |
| Volatility (vol) | +0.132 | +1.05 | 0.000 | -7.61% | 🟡 Moderate |
| Size | +0.048 | +1.25 | 0.000 | -2.06% | 🟡 Moderate |
| Earnings Yield (ep) | -0.062 | -0.74 | 0.000 | +3.87% | 🔴 Reversed |
| ROE | -0.041 | -1.23 | 0.000 | +1.11% | 🔴 Reversed |
| FCF Yield | -0.059 | -1.43 | 0.000 | +3.04% | 🔴 Strong reversal |
| Book/Price (bp) | +0.006 | +0.08 | 0.635 | +0.82% | ⚪ Ineffective |
Key Findings
- Momentum still dominates: ICIR +2.70 is the highest across all factors with 100% IC positive rate over 39 periods. Negative long-short (-8.07%) reflects low-momentum stocks underperforming — the alpha is entirely in the long leg (high momentum quintile).
- Value/quality factors fully reversed: EP, FCF Yield, and ROE all show negative IC, meaning low-valuation stocks systematically underperform. FCF Yield’s ICIR of -1.43 is the strongest inverse signal in the current regime.
- Volatility premium persists but isn’t extreme: vol factor ICIR +1.05 shows high-vol stocks carry positive excess returns, but far less reliably than momentum.
🏭 Sector Momentum Decomposition
| Sector | IC Mean | ICIR | Q1 Return | Q5 Return | Long-Short |
|---|---|---|---|---|---|
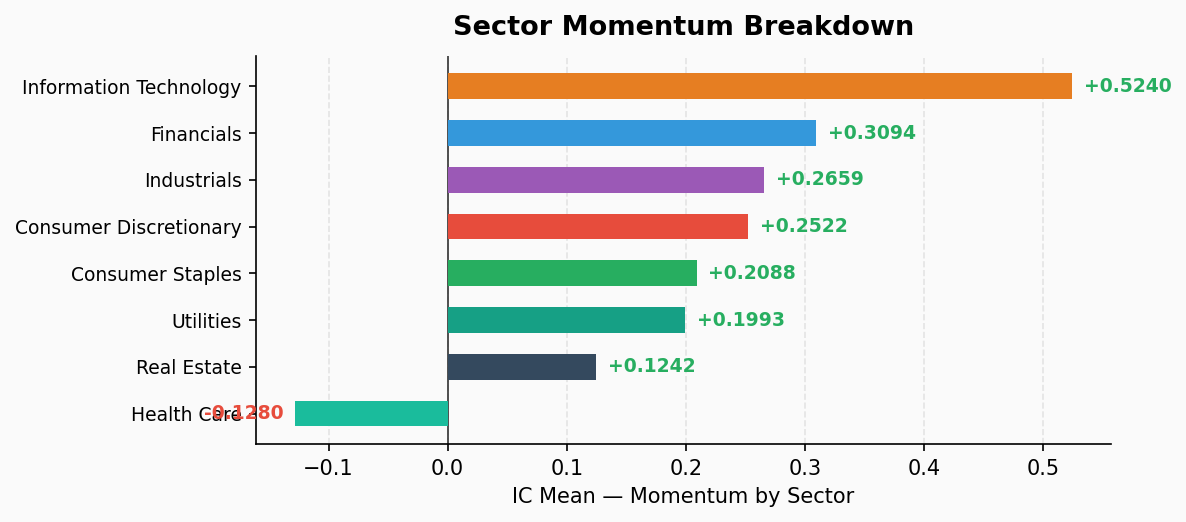
| Information Technology | +0.524 | +2.58 | -1.35% | +27.19% | -28.54% |
| Industrials | +0.266 | +2.88 | -1.63% | +5.51% | -7.14% |
| Financials | +0.309 | +2.63 | +0.61% | +7.80% | -7.19% |
| Consumer Discretionary | +0.252 | +2.11 | -4.05% | +2.15% | -6.21% |
| Consumer Staples | +0.209 | +1.34 | -4.65% | +0.02% | -4.67% |
| Utilities | +0.199 | +1.01 | -2.29% | -1.66% | -0.63% |
| Real Estate | +0.124 | +0.84 | +1.12% | +4.95% | -3.83% |
| Health Care | -0.128 | -1.21 | +4.84% | -2.66% | +7.51% |
Sector Commentary
- IT momentum is extreme: Q5 (highest momentum) delivers +27.19% monthly return vs Q1 at -1.35%. This is a +28.5pp spread — driven by mega-cap tech leadership (NVDA, MSFT, AAPL). Crowding risk is elevated.
- Health Care is the sole reversal sector: Negative IC means low-momentum healthcare stocks outperform high-momentum ones. Q1 return +4.84% vs Q5 at -2.66%. This signals mean reversion in beaten-down pharma/biotech names.
- Industrials and Financials offer reliable momentum: ICIR above +2.5 in both, second only to IT.
📝 Summary
- Momentum remains the dominant factor but only reliably effective in IT, Industrials, and Financials
- Value factors are systematically failing — low-valuation strategies underperform in a growth/momentum-driven market
- Healthcare stands out as the only sector where momentum reverses — contrarian plays in beaten-down pharma may have merit
- Risk warning: ICIR above 2.5 for momentum often precedes crowding-induced reversals; monitor for momentum crash signals