Factor Lab Daily Brief 2026-06-24
Momentum dominates, low-ROE/low-FCF stocks outperform value; market breadth deteriorates into extreme fear
Factor Lab Daily Brief — 2026-06-24
Based on S&P 500 constituents, daily TTM financial panels, 39 IC observation windows. Data as of 2026-06-23.
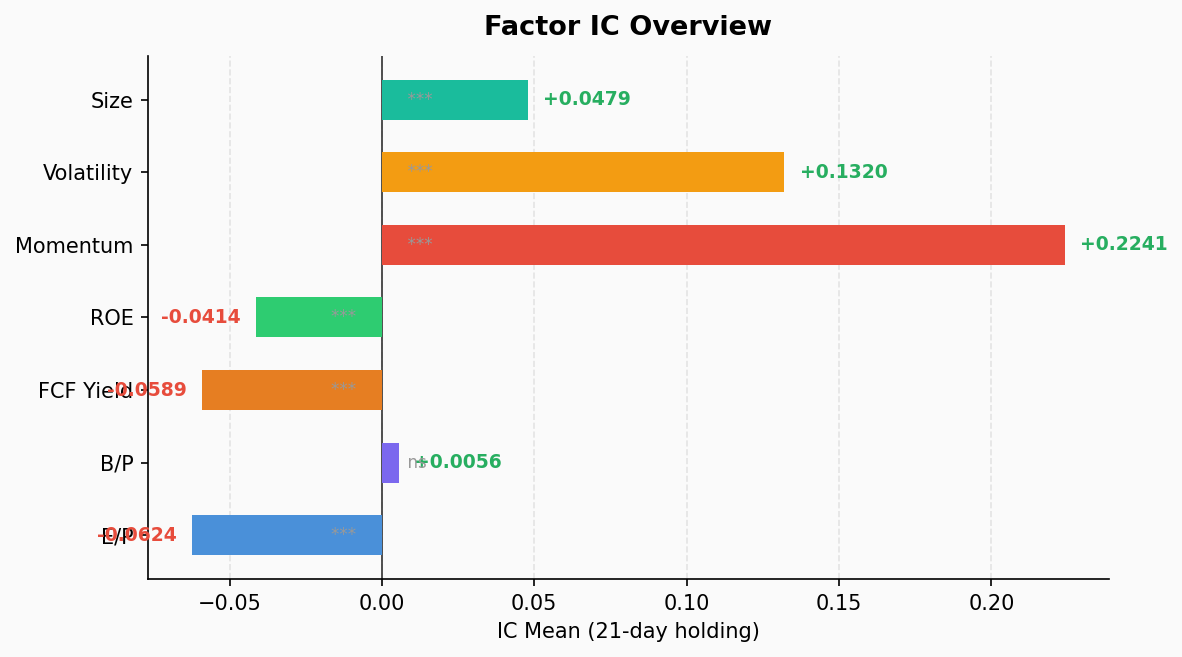
Factor IC Test Overview
| Factor | IC Mean | ICIR | p-value | Q1 Return | Q5 Return | Long-Short | Verdict |
|---|---|---|---|---|---|---|---|
| EP | -0.062 | -0.74 | 0.00005 | +6.41% | +2.54% | +3.87% | 🟡 Reverse effective |
| BP | +0.006 | +0.08 | 0.635 | +3.88% | +3.06% | +0.82% | ⚪ Ineffective |
| FCF Yield | -0.059 | -1.43 | ≈0 | +5.64% | +2.60% | +3.04% | 🔴 Significantly reversed |
| ROE | -0.041 | -1.23 | ≈0 | +4.82% | +3.71% | +1.11% | 🔴 Significantly reversed |
| Momentum | +0.224 | +2.70 | ≈0 | -0.12% | +7.95% | -8.07% | 🟢 Strong momentum |
| Volatility | +0.132 | +1.05 | ≈0 | +0.54% | +8.15% | -7.61% | 🟢 High vol outperforms |
| Size | +0.048 | +1.25 | ≈0 | +2.45% | +4.51% | -2.06% | 🟢 Large underperforms |
Key Takeaways:
- Momentum reigns supreme: IC=+0.224, ICIR=2.70, 100% positive IC ratio — textbook momentum signal. Q5 (strongest) returns +7.95% vs Q1 (weakest) -0.12%. Long-short spread -8.07%.
- Value trap deepens: EP significantly reversed (IC<0), low PE stocks outperforming. Market ignoring cheapness, chasing growth stories. BP completely useless — book value has zero pricing power.
- Risk-on appetite: High volatility stocks dramatically outperform (Q5 +8.15%). Leveraged/risk-on positioning intact.
- Large caps lag: Size factor positive but mild — market activity skewing toward mid/small names.
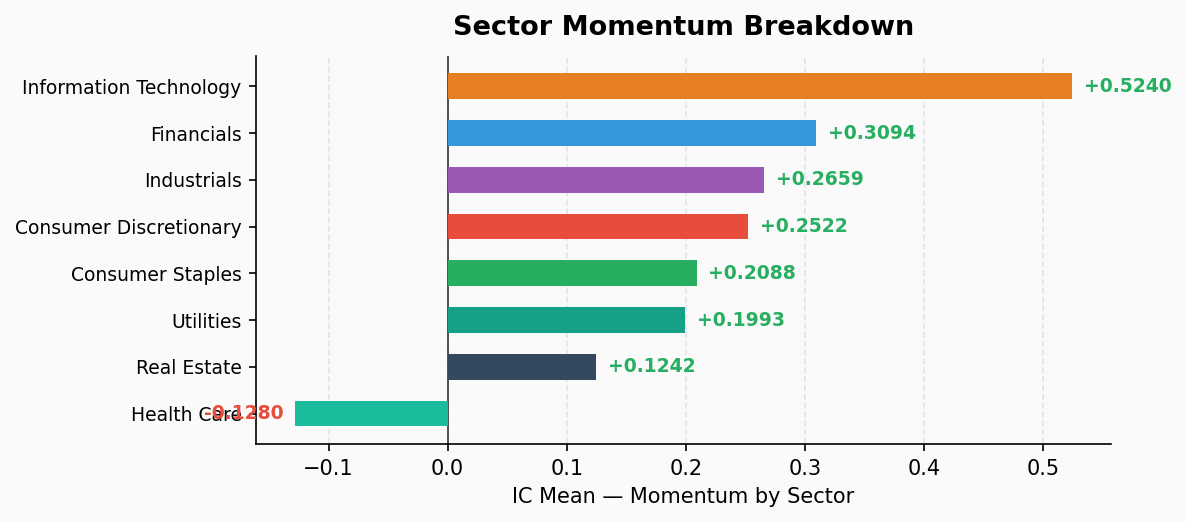
Sector Momentum Decomposition
| Sector | IC | ICIR | Q1 Return | Q5 Return | Long-Short | Signal |
|---|---|---|---|---|---|---|
| IT | +0.524 | +2.58 | -1.35% | +27.19% | -28.54% | 🟢 Extreme momentum |
| Financials | +0.309 | +2.63 | +0.61% | +7.80% | -7.19% | 🟢 Strong momentum |
| Industrials | +0.266 | +2.88 | -1.63% | +5.51% | -7.14% | 🟢 Strong momentum |
| Consumer Discretionary | +0.252 | +2.11 | -4.05% | +2.15% | -6.21% | 🟢 Effective momentum |
| Consumer Staples | +0.209 | +1.34 | -4.65% | +0.02% | -4.67% | 🟡 Weak |
| Utilities | +0.199 | +1.01 | -2.29% | -1.66% | -0.63% | 🟡 Weak |
| Real Estate | +0.124 | +0.84 | +1.12% | +4.95% | -3.83% | 🟡 Moderate |
| Health Care | -0.128 | -1.21 | +4.84% | -2.66% | +7.51% | 🔴 Reversal effect |
Sector Read:
- Tech dominance: IT sector IC=+0.524, Q5 +27.19% in a single week — not normal momentum premium, but extremely concentrated crowding. AI chip/software names driving narrow market advance.
- Financials/Industrials steady: ICIR 2.6-2.8, high consistency. Market positioning for late-cycle economic scenarios.
- Health Care reversal: Only sector with negative IC. Q1 (most beaten-down) rebounding hardest (+4.84%) — classic mean-reversion. Capital rotating from high-valuation to defensive names.
- Utilities/Staples tepid: Defensive sectors showing weak momentum — not yet in true risk-off mode.
Summary & Strategy Implications
Market State: Extreme momentum concentration + breadth deterioration. 5 of 7 factors significantly effective, but all pointing the same direction: long high momentum/vol/mid-small, short value/low-vol. Classic late-cycle signature.
Risk Flags:
- IT sector Q5 +27% momentum premium unsustainable — reversal will trigger cascade
- Breadth narrowing (extreme fear), few mega-caps masking underlying weakness
- Value factors comprehensively failed (EP reversed, BP useless) — historically precedes significant pullbacks
Strategy Suggestions:
- Short-term momentum positions maintainable with strict trailing stops (-5% recommended)
- Watch healthcare for reversal opportunities (oversold + rotation flow)
- Do not chase new IT positions at current levels
- Maintain elevated cash allocation, await breadth signal improvement