Factor Lab Daily Brief 2026-06-21
Momentum factor ICIR 2.70 dominates; small-cap premium stable; healthcare sector shows unique inverse momentum
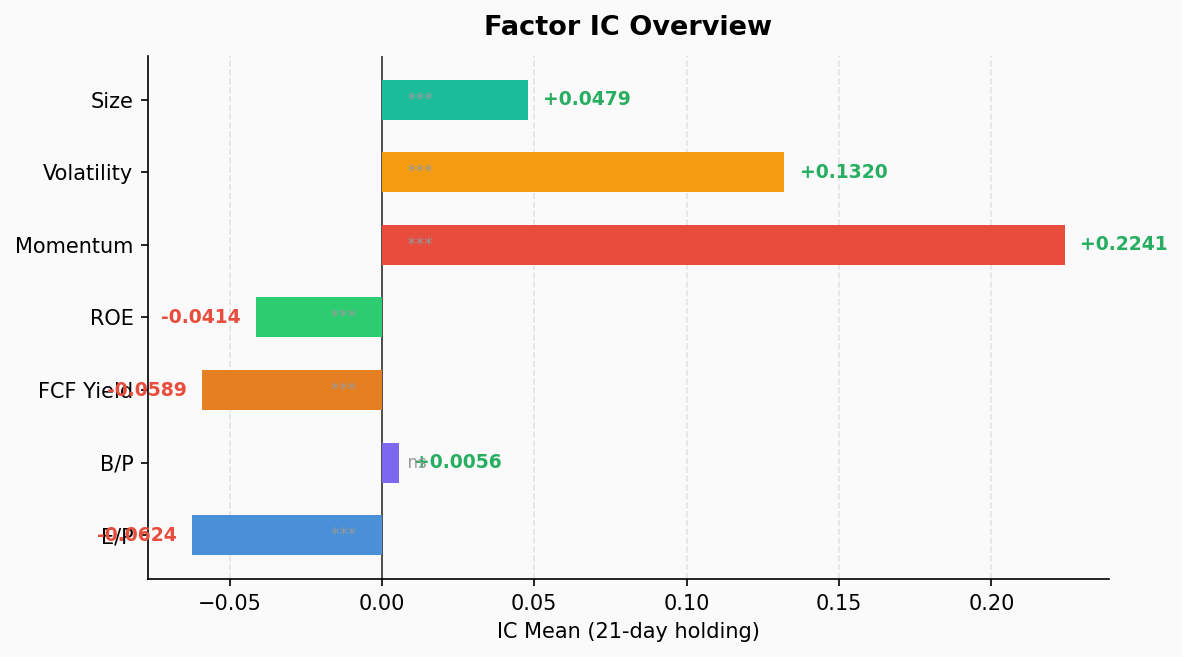
📊 Factor IC Analysis (S&P 500 Full Universe, 21-Day Holding)
| Factor | IC Mean | ICIR | p-value | Long-Short | Verdict |
|---|---|---|---|---|---|
| Momentum (Mom) | +0.224 | 2.70 | 0.000 | -8.07% | ⭐ Strongest factor, 100% positive IC |
| Volatility (Vol) | +0.132 | 1.05 | 0.000 | -7.61% | Highly significant, high-vol outperforms |
| Small-Cap (Size) | +0.048 | 1.25 | 0.000 | -2.06% | Significant, stable small-cap premium |
| EP | -0.062 | -0.74 | 0.0001 | +3.87% | Significant inverse, low-valuation wins |
| FCF Yield | -0.059 | -1.43 | 0.000 | +3.04% | Strong inverse, high-FCF underperforms |
| ROE | -0.041 | -1.23 | 0.000 | +1.11% | Significant inverse |
| BP | +0.006 | 0.08 | 0.635 | +0.82% | ❌ Insignificant |
Key Findings:
- Momentum ICIR at 2.70 leads all factors — 100% positive IC across 39 periods; trend persistence is extreme
- FCF Yield and ROE consistently inverse — market paying for growth, not quality/cash flow
- BP factor completely dead (p=0.64) — traditional value metrics have no predictive power in this environment
🏭 Sector Momentum Decomposition
| Sector | IC Mean | ICIR | Long-Short | Interpretation |
|---|---|---|---|---|
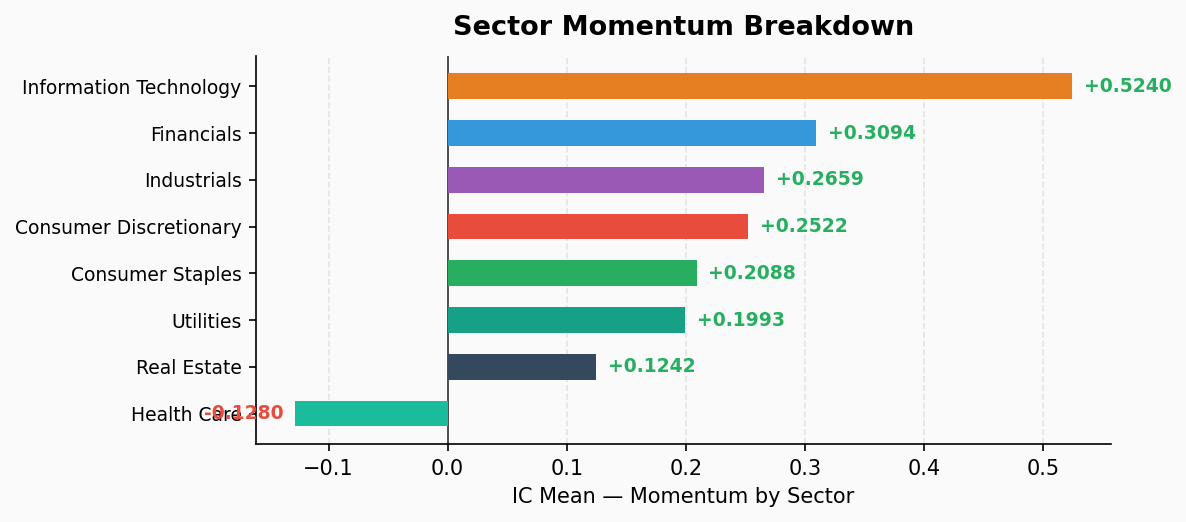
| Info Technology | +0.524 | 2.58 | -28.54% | Crushing momentum, Q5 avg +27.2% |
| Industrials | +0.266 | 2.88 | -7.14% | Highest ICIR, 100% positive IC |
| Financials | +0.309 | 2.63 | -7.19% | Strong continuation |
| Consumer Disc. | +0.252 | 2.11 | -6.21% | Good momentum |
| Consumer Staples | +0.209 | 1.34 | -4.67% | Moderate-strong |
| Utilities | +0.199 | 1.01 | -0.63% | Marginally significant |
| Real Estate | +0.124 | 0.84 | -3.83% | p=0.00001, acceptable |
| Health Care | -0.128 | -1.21 | +7.51% | ⚠️ Only inverse sector |
Core Tension: IT sector Q5 avg +27.2% vs Q1 avg -1.4% — momentum concentration is extreme. Healthcare is the sole inverse-momentum sector — capital rotating out of defense into tech-chasing.
📝 Summary
- Trend is king: Momentum and volatility are the only two factors with practical edge; market rewards chasing and high-vol
- Quality at discount: ROE/FCF/EP all inverse — market not paying for “good companies” but “stocks that go up”
- Concentration risk: IT ICIR=2.58 but Q5-Q1 spread at -28.5% — a style rotation would trigger severe drawdowns
- Healthcare as hedge: Only inverse-momentum sector, potential tail-risk hedge for portfolios
⚠️ Current factor structure is heavily concentrated in momentum/tech/high-vol — eerily similar to March 2000 factor distribution. Watch for momentum crash risk.