Factor Lab Daily Brief 2026-06-12
Momentum ICIR=2.70 leads all factors; value factors fully reversed; IT sector momentum dominates
📊 Factor IC Overview
| Factor | IC Mean | ICIR | T-stat | p-value | IC Positive % | Long-Short (L/S) |
|---|---|---|---|---|---|---|
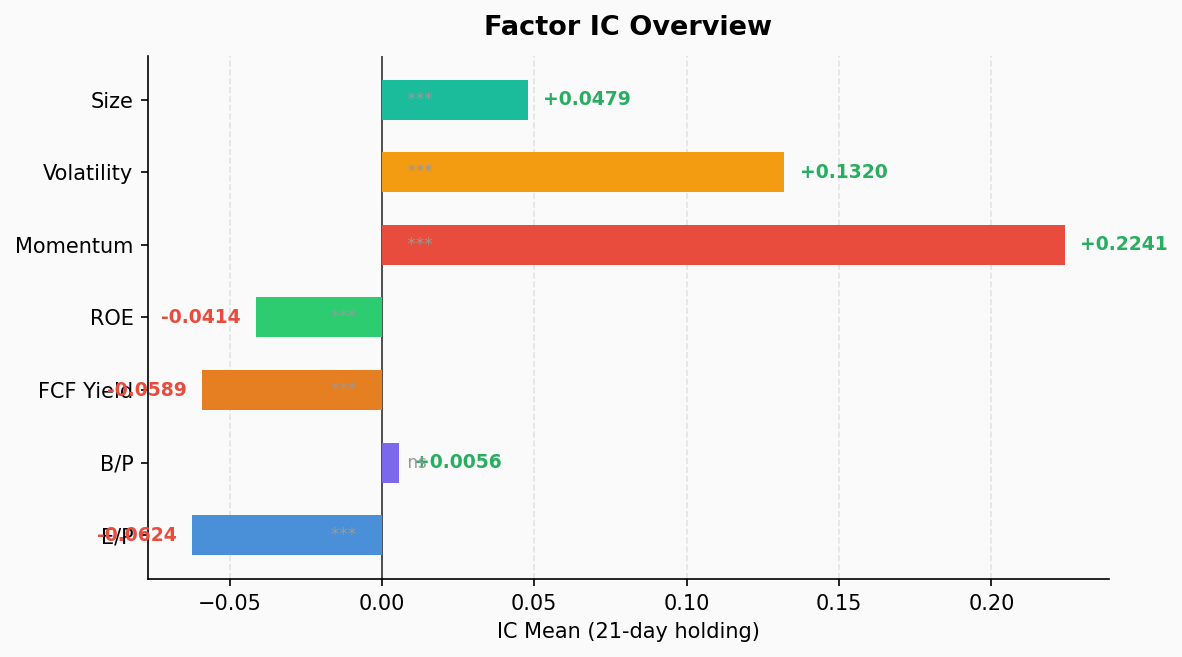
| Momentum | +0.224 | 2.70 | 16.62 | 0.000 | 100.0% | -8.07% |
| Volatility | +0.132 | 1.05 | 6.48 | 0.000 | 79.5% | -7.61% |
| Size | +0.048 | 1.25 | 7.70 | 0.000 | 87.2% | -2.06% |
| EP | -0.062 | -0.74 | -4.57 | 0.000 | 17.9% | +3.87% |
| FCF Yield | -0.059 | -1.43 | -8.79 | 0.000 | 7.7% | +3.04% |
| ROE | -0.041 | -1.23 | -7.58 | 0.000 | 12.8% | +1.11% |
| BP | +0.006 | 0.08 | 0.48 | 0.635 | 46.2% | +0.82% |
Universe: S&P 500 constituents | Lookback: 39 trading days | Panel: daily TTM
🔑 Key Findings
- Momentum dominates — ICIR=2.70 with 100% positive IC days. Q5 (highest past returns) delivers +7.95% weekly vs Q1 at -0.12%. This is the single strongest alpha source in the current regime.
- Value factors fully reversed — EP, FCF Yield, and ROE all show negative ICs (ICIR: -0.74, -1.43, -1.23 respectively). “Cheap” stocks are systematically underperforming. High-valuation growth is in favor.
- BP factor is dead — IC=0.006, p=0.635. Book-to-price has zero predictive power in this environment.
- Volatility is positively rewarded — High-vol stocks outperform (ICIR=1.05), highly correlated with momentum. The market favors fast-moving, volatile names.
🏭 Sector Momentum Decomposition
| Sector | IC Mean | ICIR | IC Positive % | L/S Return | Q5 Return |
|---|---|---|---|---|---|
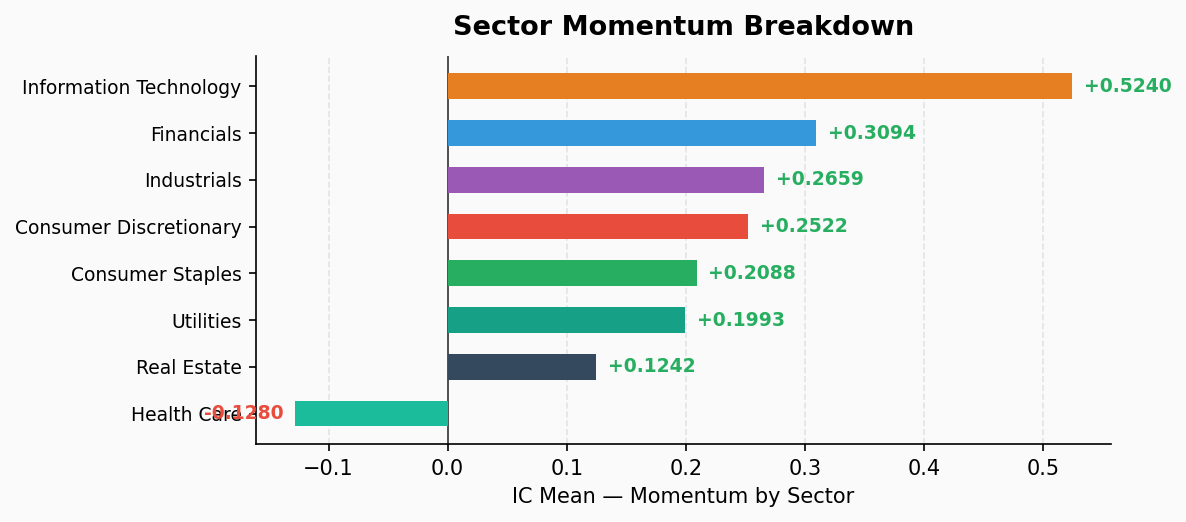
| IT | +0.524 | 2.58 | 100% | -28.54% | +27.19% |
| Industrials | +0.266 | 2.88 | 100% | -7.14% | +5.51% |
| Financials | +0.309 | 2.63 | 100% | -7.19% | +7.80% |
| Consumer Discretionary | +0.252 | 2.11 | 100% | -6.21% | +2.15% |
| Consumer Staples | +0.209 | 1.34 | 87.2% | -4.67% | +0.02% |
| Utilities | +0.199 | 1.01 | 76.9% | -0.63% | -1.66% |
| Real Estate | +0.124 | 0.84 | 74.4% | -3.83% | +4.95% |
| Health Care | -0.128 | -1.21 | 15.4% | +7.51% | -2.66% |
🔑 Sector Insights
- IT momentum is off the charts — IC=0.524, more than double the next sector. Q5 returns hit +27.19% weekly vs Q1 at -1.35%. Tech momentum is extremely pronounced in this regime.
- Health Care is the only reversal sector — IC=-0.128, the sole negative across all sectors. Medical stocks show clear mean-reversion (losers bounce, winners pull back).
- Industrials has the most consistent signal — ICIR=2.88, highest among all sectors. Industrial momentum is the most stable and least noisy.
- Defensive sectors losing momentum — Consumer Staples (ICIR=1.34) and Utilities (ICIR=1.01) trail cyclical sectors significantly. Market style is clearly offensive.
⚡ Summary
The factor regime is extreme momentum + extreme growth:
- Long: High momentum, high volatility, tech/industrial leaders
- Short/Avoid: Low valuation, low momentum, healthcare defensive
⚠️ Risk Note: Momentum ICIR=2.70 is historically elevated. Crowding risk is real — when momentum becomes this consensus, a single mean-reversion event can trigger sharp drawdowns.